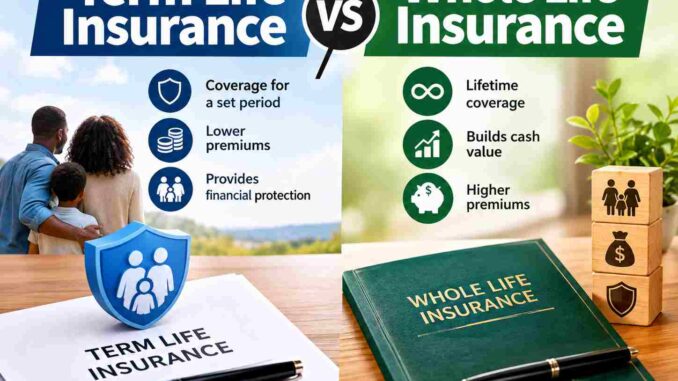
Term life vs whole life insurance is one of the biggest choices facing American families. Term life covers you for a fixed period, such as 10, 20 or 30 years. Whole life covers you for your entire life and builds a savings component called cash value. The main trade-off is cost. Term is far cheaper, but whole life lasts for life.
Term life pays a death benefit only if you die during the policy period. It has no cash value. As a result, it is often called pure life insurance. Premiums stay level for the term, and some policies can be converted later to permanent cover.
Whole life pays out whenever you die, as long as premiums are paid. Premiums stay level for life. Part of each payment builds cash value, which grows at a guaranteed rate. Some insurers also pay dividends, which are not guaranteed. You can borrow against the cash value while you are alive. However, unpaid loans reduce the death benefit.
Term vs whole life at a glance
| Feature | Term life | Whole life |
|---|---|---|
| Coverage length | 10, 20 or 30 years | Your whole life |
| Monthly cost* | About $25 to $55 | About $350 to $550 |
| Cash value | None | Yes, growing slowly |
| Premiums | Level for the term | Level for life |
| If you outlive the policy | No payout | Not applicable; it lasts for life |
| Often chosen by | Families needing large cover on a budget | People wanting lifelong cover and guarantees |
*Estimates for $500,000 of cover for a healthy 35-year-old, from 2026 industry comparison sites. Prices vary by insurer, age and health.
Cost is the biggest gap. Industry comparisons put whole life at about 5 to 15 times the price of term for the same death benefit. For a healthy 35-year-old, $500,000 of term cover may cost roughly $25 to $55 a month. The same amount of whole life may cost $350 to $550.
Cash value grows slowly in the early years. Guaranteed growth is typically in the low single digits, so it can take years before the balance is worth using. Also, beneficiaries usually receive the death benefit and not the cash value on top, unless a rider says otherwise.
Many financial writers suggest buying term and investing the difference. That approach can build more wealth if investment returns beat whole life’s guaranteed rate. However, investment returns are not guaranteed. Whole life suits people who want lifelong cover, a guaranteed outcome or estate planning tools. Others may find term enough while children are young or a mortgage is running.
Before you decide, ask about the insurer’s AM Best rating and the policy’s guarantees and fees. Also ask whether you can convert term cover to permanent cover later. In addition, compare quotes from several insurers. A licensed agent or fee-only adviser can help match a policy to your needs.
This article is for information only and is not financial or insurance advice. Prices and policy terms differ by insurer and state.
Leave a Reply